 IGNITE
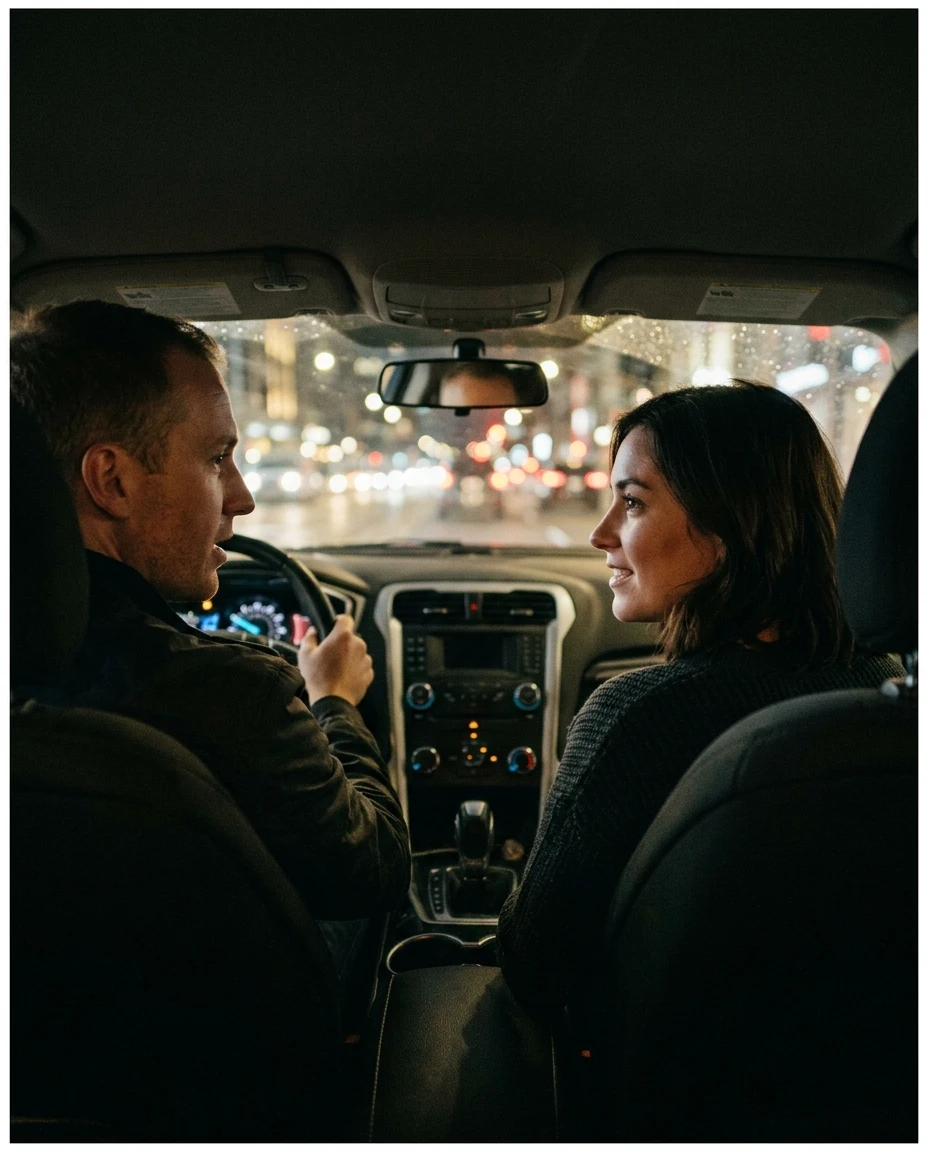
It was dark, we'd just left dinner with old friends, and my wife asked me the question in that disarmingly casual tone she saves for the ones that actually matter. "Was it worth it? Both of them?" She meant the accelerators. Two of them, years apart, running on completely different rulebooks. I sat there in the passenger seat wanting to give a one-word answer, knowing the real answer needed a paragraph. Maybe an essay. Maybe this whole post.
Here's my hard take before we go any further: the equity-versus-free debate that dominates every "how to choose an accelerator program" article online is mostly a distraction. It feels like the big decision because it's the number you can point to on a page. But that number isn't what determines whether a program actually helps you build something. The business model behind the accelerator is what determines that. Figure out what the program needs to produce to survive, and you'll know exactly what you're going to get out of it, equity or no equity on the table.
Two accelerators, two very different bets
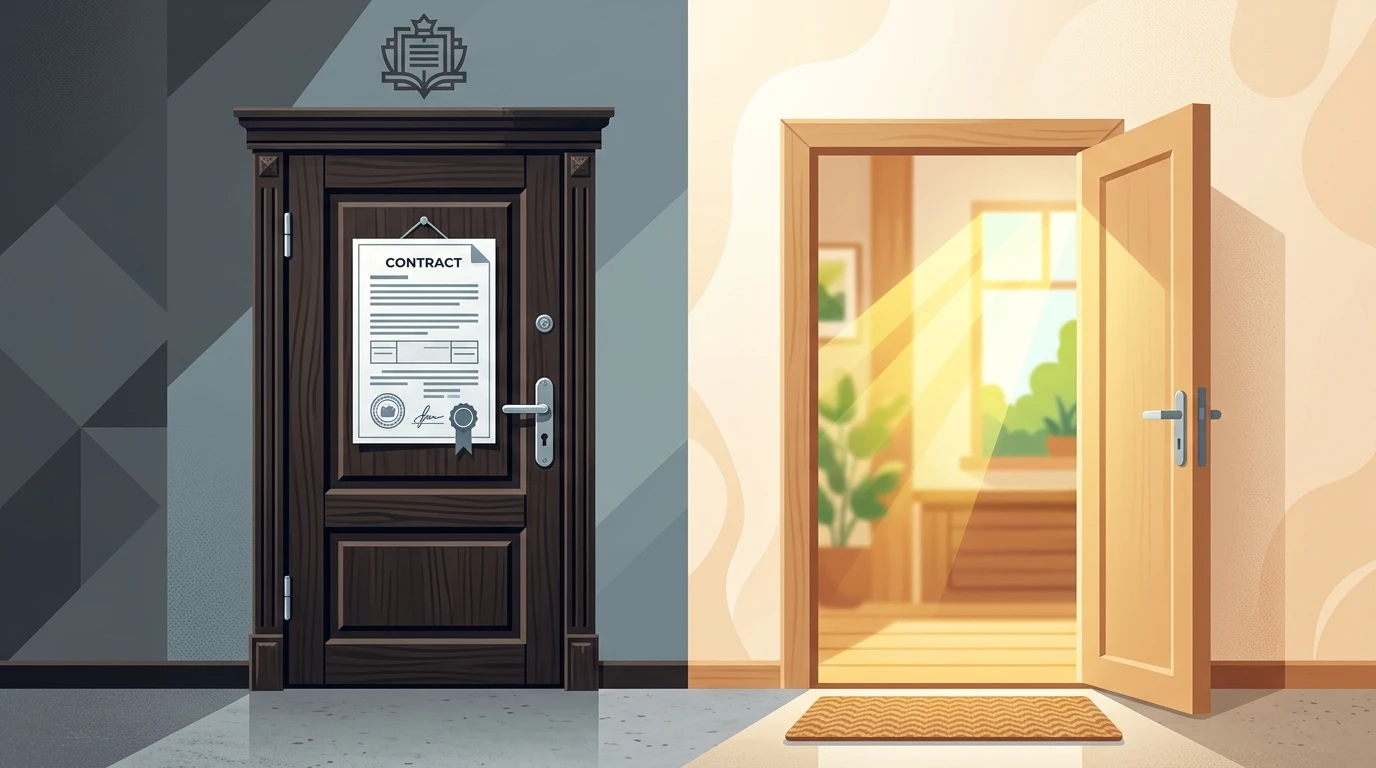
The first one was Founder Institute, and it wanted a piece of my company. Not at signup, which surprised me. You don't get handed the full equity agreement on day one. It shows up roughly two-thirds of the way through the program, after you've already sat through the mentor sessions and started to see whether the network was worth anything to you. The ask is 2.5% of future equity, structured as a warrant into something they call the Equity Collective, split among mentors, local chapter leads, and the organization itself. You can actually read the agreement terms before you sign anything. I did, twice, because "selling your soul to the devil" was the phrase running through my head the entire time, and I wasn't about to sign that away on vibes.
The second one was a government-backed program out of Kitchener, Ontario, tied to the University of Waterloo. Zero equity. Zero fees. Three months, with the possibility of a non-repayable grant depending on the cohort. The Summer Accelerator program page lays out exactly what they offer and exactly what they don't ask for, which is refreshing after wading through a dozen "partner with us" pages that bury the actual terms in a PDF nobody clicks.
So which one was better? Wrong question. That's the trap. The right question is why each one is structured the way it is, and what that structure is quietly optimizing for.
The real due diligence is asking how they make money
Founder Institute makes money and builds its network on the long tail of founders who eventually raise or exit. Their incentive is to get you fundraising-ready, get you talking like an investor wants to hear, get you into a pattern that produces a good demo day story. That's not a knock, it's just the mechanism. If your company's actual bottleneck is closing your first real customers or fixing a broken sales process, a program built around fundraising fluency is going to feel oddly disconnected from your day to day, even while the mentor calls feel great.
Velocity's incentive is different because it's not chasing equity, it's chasing regional economic outcomes. A university-backed, government-funded accelerator wants job creation, local company survival rates, and headlines about founders staying in the region instead of leaving for Silicon Valley or Toronto. That means the advice skews toward operational survival and local hiring, not toward optimizing your pitch deck for a Series A you may not even want.
Neither model is evil. But neither one is neutral either. This is the actual due diligence most founders skip when they're wading through startup funding options explained on some blog somewhere: not "is this equity or free," but "what does this organization need me to become in order for their model to work." That's how you properly evaluate an accelerator's business model, by working backward from the incentive instead of forward from the marketing page.
I learned this lesson the hard way once already, when a design agency I got routed to through a different accelerator kept pitching me CRM solutions after I'd told them three separate times that what I'd built wasn't a CRM. That's its own story, and I wrote about it in more detail in what happens when an accelerator hands you a pseudo-expert instead of someone who actually reads the documentation. The lesson generalizes: an accelerator's brand doesn't guarantee the person on the other end of the introduction actually understands your business. You still have to vet everything they hand you.
The fine print checklist I wish I'd had the first time
If you're staring at an accelerator offer letter right now, trying to make an early-stage startup decision under a deadline, here's the actual checklist, not vibes:
- Trigger events. When does the equity or fee actually kick in? Founder Institute's ask lands later in the program specifically so you can judge the network's value first. Know when your clock starts.
- Dilution mechanics. Understand the basics of startup equity and dilution before you sign anything, specifically whether the stake is a flat percentage, a warrant, or convertible into something else down the line.
- IP clauses. Who owns what you build during the program? Read this section twice, out loud, ideally to someone who isn't emotionally invested in getting into the cohort.
- Exit conditions. Can you leave the program early, and does that change what you owe? Some agreements assume you'll finish and never spell out what happens if you don't.
- What happens if you never raise. If the whole equity structure is contingent on a future raise that never happens, get that in writing.
None of this is exciting. All of it matters more than the alumni list on the homepage.
Not every founder needs the fundraising version
Here's where I'll push back on almost everything written about accelerators, including some of the research behind this piece. Most of that content, and honestly most accelerators themselves, are built for venture-scale startups chasing a raise. If you're running a profitable mid-size business, the honest question isn't "can this help me raise seed funding." It's "can this help me sell more, hire better, or expand into a new market." Those are different problems with different solutions, and a program obsessed with pitch decks isn't going to move the needle on either one.
This matters even more if bootstrapping versus venture capital was never really an open question for you in the first place, because your business already throws off cash. In that case, an accelerator's real value isn't access to investors, it's access to a peer group and mentors who've already made the calls you're about to make, on scaling a startup team, on picking your first hires, on when a pivot actually beats persevering versus when persevering is just stubbornness wearing a business plan. I've made bad hires before I understood that lesson, which is part of why I eventually wrote about the freelancers I stopped hiring and what that pattern finally taught me about vetting people before they touch your business.
The research backs the nuance, not either extreme
A recent NBER working paper found that accelerated startups raised roughly $530,000 more in post-program funding on average compared to startups that skipped the program entirely, with only about 8% of the non-accelerated group ever landing venture financing at all. That's a real number, and it's the strongest argument for the fundraising-heavy model if raising is actually your goal.
But a separate study on founders' pre-entry knowledge found the benefits are uneven. Founders who already knew how to convert mentorship and introductions into actual traction saw meaningfully better growth from the same program than founders who walked in without that foundation. Translation: an accelerator amplifies what you already know how to do. It rarely builds that capability from zero. If you can't tell a good investor from a bad one before you enroll, a room full of investors won't fix that for you. It'll just speed up the mistake. Choosing the right investors is a skill you build before the accelerator, not inside it, and the same instinct is what separates a mentor coaching you toward a real close from one just running a script. I think about this the same way I think about sales conversations generally, which is why the difference between closing tricks and earning trust shows up in accelerator mentor rooms just as often as it shows up on a sales call.
So, was it worth it?
Back to the car. My honest answer to my wife, and to you if you're weighing this right now, is yes, both were worth it, for completely different reasons. Founder Institute sharpened how I talked about the business and forced some discipline into how I thought about growth, even though the equity ask made me read every clause twice. Velocity gave me a peer group and operational support at zero cost, which is its own kind of gift when you're trying to avoid the mistakes that come from building in isolation.
Neither program built my growth strategy for me. I built that on my own, later, by actually shipping things and testing what worked before spending a dollar on ads, a story I've told in more detail around how we generated our first qualified leads with zero ad spend. What the accelerators did was speed up the parts I already had some instinct for, and expose the parts I didn't.
So before you sign anything, equity clause or not, skip the debate about which model sounds more generous. Ask what the organization is actually built to produce, ask whether that output is the one your business needs right now, and read the fine print like your future ownership stake depends on it. It might.
What would you actually be trading, and do you know who's on the other side of that trade?
FAQ
Is an equity-based accelerator worse than a free one?
Not necessarily. What matters more is the business model behind the program, since that determines what advice and outcomes you'll actually get, not whether equity changes hands.
When did Founder Institute actually ask for equity?
The ask shows up roughly two-thirds of the way through the program, after mentor sessions have already happened, and it's structured as a 2.5% warrant into their Equity Collective.
Does Velocity's accelerator really charge nothing?
Yes, it's a government-backed, university-tied program out of Kitchener, Ontario with zero equity and zero fees, running three months with a possible non-repayable grant.
What should I actually check before signing an accelerator agreement?
Look at trigger events, dilution mechanics, IP clauses, exit conditions, and what happens if you never raise, since those details matter far more than the alumni list.
Do accelerators actually help you raise more money?
An NBER working paper found accelerated startups raised roughly $530,000 more on average than non-accelerated ones, but the benefit skews toward founders chasing venture-scale funding.
Is an accelerator worth it if I'm not trying to raise venture capital?
It can be, but the value shifts from investor access to peer support and operational advice, so it depends on whether your bottleneck is fundraising or things like sales, hiring, or expansion.